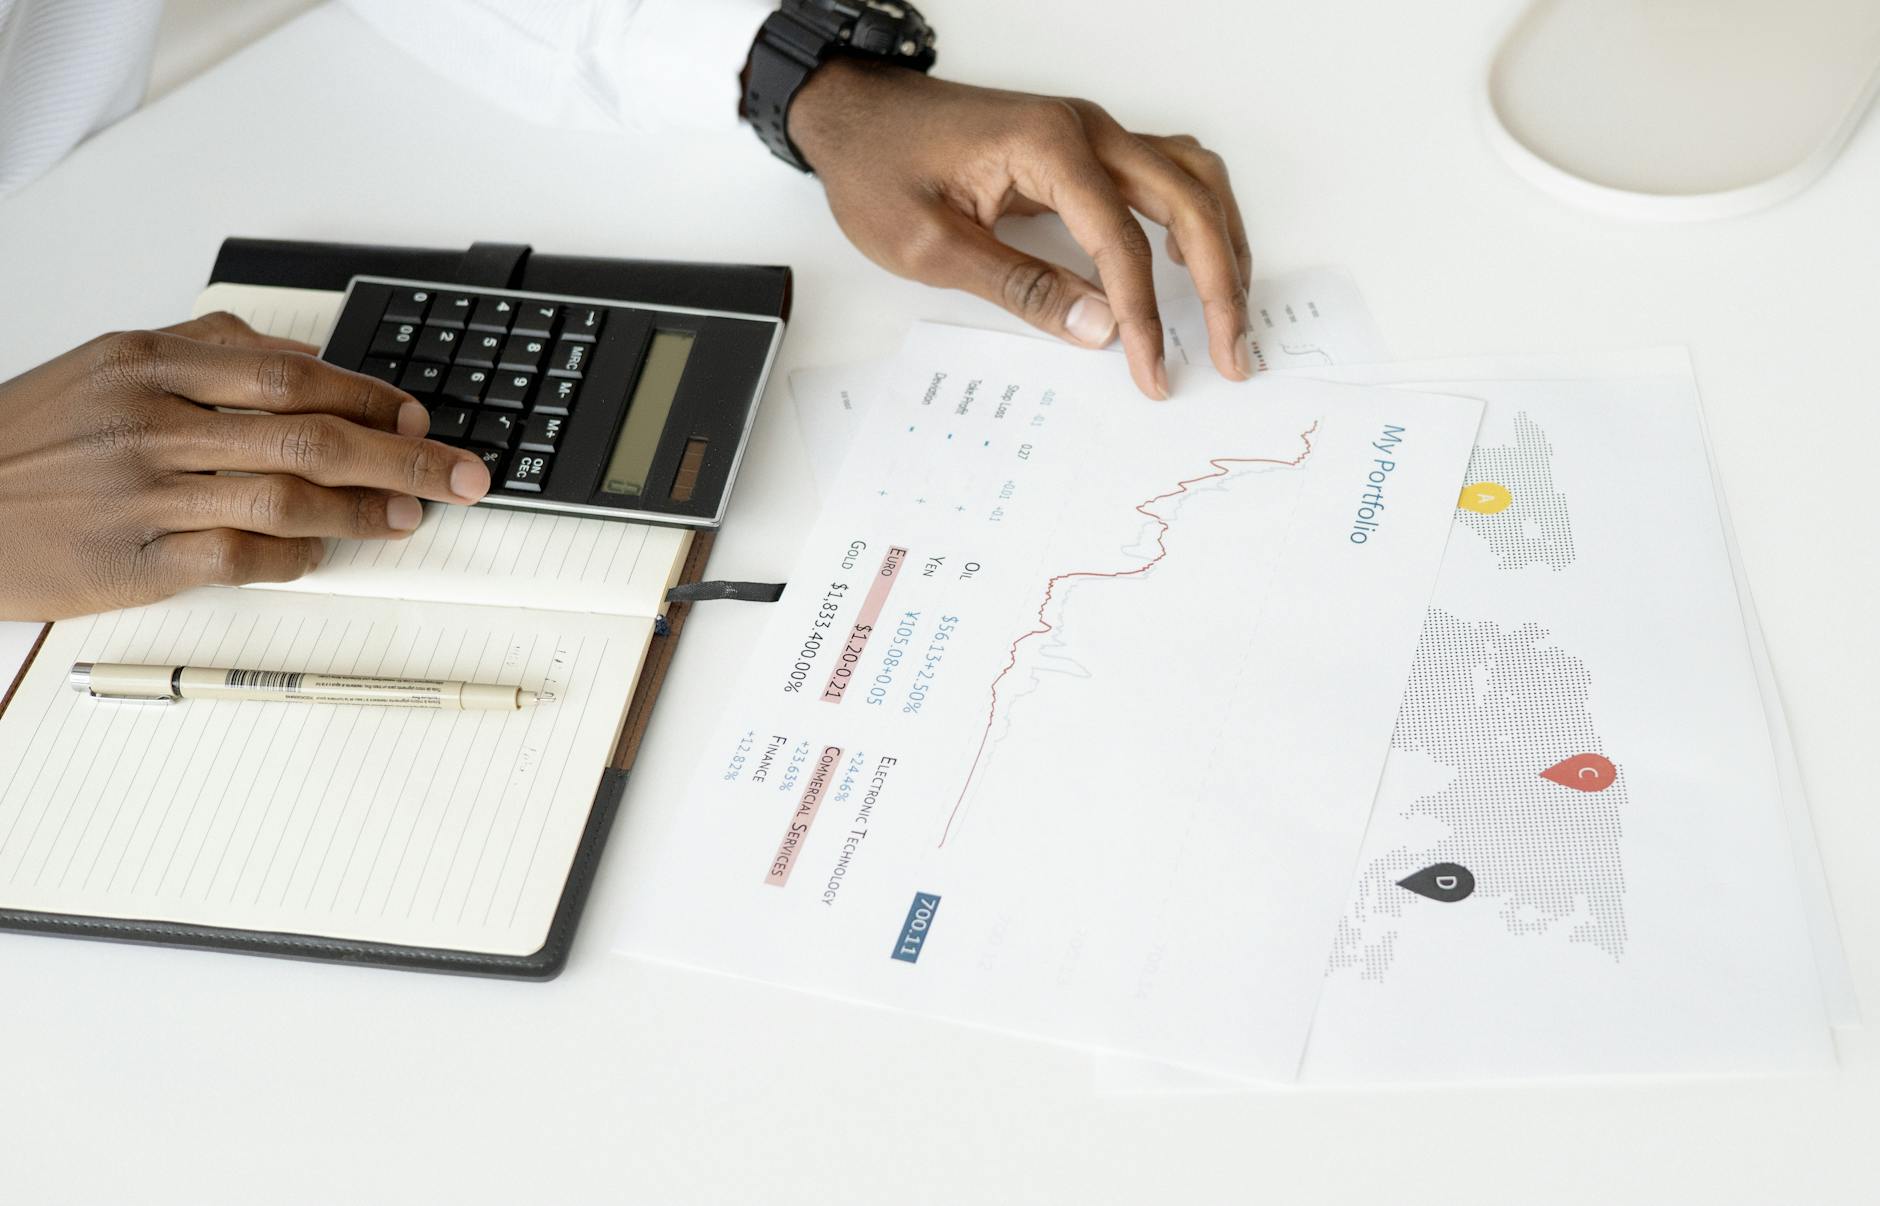
Boost Your Portfolio: Beat 2% Inflation Now!
Are you feeling a nagging sense that your investments aren't quite keeping pace? Maybe your returns haven’t been as impressive as you’d hoped, and you’re starting to wonder if you’re getting the most out of your portfolio. The culprit might not be a bad market, but a simple shift in your asset allocation. In today’s environment of 2% inflation, regularly rebalancing your portfolio is no longer a nice-to-have – it’s a necessity for preserving your purchasing power and achieving your long-term financial goals.
Understanding Inflation and Portfolio Drift
Inflation, the rate at which the general level of prices for goods and services is rising, erodes the value of your investments over time. If your investments are growing at a rate slower than inflation, you’re essentially losing buying power. This phenomenon is known as “portfolio drift.” As asset classes perform differently, the proportions of your portfolio shift. For example, if stocks outperform bonds, your stock allocation will increase, even if you haven’t intentionally changed your investment strategy. A small shift like this can have a significant impact over several years.
According to the U.S. Bureau of Labor Statistics, inflation has averaged around 2.5% over the past 30 years. While this is an average, it’s a crucial benchmark for understanding the challenges investors face. Let’s look at a simplified example. Suppose you initially invested $10,000, allocated 60% to stocks and 40% to bonds. If stocks return 10% and bonds return 2% in a year, your portfolio grows to $11,000. However, because of inflation, the real value of that $11,000 is actually less than the original $10,000 – it’s equivalent to only $9,550.
Why Rebalancing Matters
Rebalancing is the process of restoring your portfolio back to its original target asset allocation. It’s essentially “buying low and selling high” – but not in a frantic, emotional way. Instead, it’s a disciplined, systematic approach designed to mitigate the effects of portfolio drift and maintain your desired risk level. Here's why it’s so important:
- Preserves Purchasing Power: By selling over-performing assets and buying under-performing ones, you ensure your investments continue to grow in line with your goals, even when inflation is present.
- Reduces Risk: Over time, asset allocations can become skewed, leading to increased risk. Rebalancing brings your portfolio back to its intended risk profile, aligning it with your comfort level and investment time horizon.
- Disciplined Investing: Rebalancing forces you to step back and evaluate your portfolio, preventing impulsive decisions driven by market fluctuations.
“Rebalancing is not about trying to time the market,” says Christine Benz, Morningstar’s director of personal finance. “It’s about sticking to your long-term plan.”
How to Rebalance Your Portfolio
There are several methods for rebalancing, but here's a practical approach:
- Determine Your Target Allocation: This is the foundation of your rebalancing strategy. A common starting point is a 60/40 stock/bond allocation, but the optimal allocation depends on your risk tolerance, time horizon, and financial goals. Use a risk assessment questionnaire to help determine your appropriate asset mix.
- Set a Rebalancing Frequency: There’s no one-size-fits-all answer. Many investors rebalance annually, while others prefer to do it quarterly or semi-annually. A good rule of thumb is to rebalance whenever your portfolio drifts by 5% or more from its target allocation. More frequent rebalancing can increase transaction costs, so consider the trade-off.
- Implement the Rebalance: When rebalancing, you’ll sell a portion of the assets that have exceeded their target allocation and use the proceeds to buy more of the assets that have fallen below. For example, if your target allocation is 60% stocks and your portfolio has drifted to 70% stocks due to stock market gains, you would sell some stocks and buy some bonds to bring the allocation back to 60/40.
- Consider Tax Implications: Rebalancing can trigger capital gains taxes. To minimize tax liabilities, consider rebalancing within tax-advantaged accounts like 401(k)s or IRAs. Holding gains in taxable accounts until you’ve met your annual contribution limits can also be a strategy.
Using a brokerage account with automated rebalancing tools can greatly simplify the process. Many platforms offer features that automatically monitor your portfolio and execute trades to maintain your target allocation.
Practical Examples of Rebalancing
Let's say you have a portfolio with the following target allocation: 50% Stocks, 40% Bonds, 10% Real Estate.
- Scenario 1: Stocks Perform Well After one year, your portfolio has grown to 60% stocks due to strong stock market performance. To rebalance, you would sell $6,000 worth of stocks and use the proceeds to buy $4,000 worth of bonds and $1,000 worth of real estate.
- Scenario 2: Bonds Perform Well Conversely, if bonds performed exceptionally well, you would sell bonds to rebalance back to your target allocation.
Key Takeaway: Rebalancing is Your Friend
In an environment characterized by persistent inflation, actively managing your portfolio through rebalancing is paramount. Don’t let your investments become victims of portfolio drift. By regularly restoring your asset allocation, you can safeguard your purchasing power, reduce risk, and increase the likelihood of achieving your long-term financial goals. Rebalancing isn’t about predicting the future; it’s about being proactive and disciplined in protecting your investments.
SmartInvestDaily.com provides resources and education to help you master your investment journey. Start building your portfolio today!
Keep Reading
Get Smarter About Money
Join thousands of investors getting daily insights delivered to their inbox.